MGM Resorts shares sank 10% in premarket trade on Thursday after Barry Diller's People Inc walked away from its $18-billion-plus takeover bid for the casino operator, erasing every dollar of the rally the offer had sparked, Reuters reported.
At $33.69, the stock was at its weakest in seven months, taking it back below where it traded before People made its approach.
People, which already holds 27% of MGM, had offered $48.30 a share for the rest of the company in June, a bid that sent MGM to an 18-year high. The deal would have pushed Diller's group, home to brands such as People magazine and Travel + Leisure, well beyond its traditional media turf.
People offered no specific reason for pulling out. Diller said, "We didn't feel the mix was coming together in the way we had hoped."
The bid was the second attempt this year to take a casino operator private, after hospitality billionaire Tilman Fertitta struck a deal in May to buy out Caesars Entertainment, according to Reuters report.
The Street had largely backed the tie-up. Truist Securities analysts said MGM, under People's ownership, "could potentially operate better under less short-term focused investor scrutiny."
People Inc shares, down a fifth since Diller first floated the proposal, were flat.
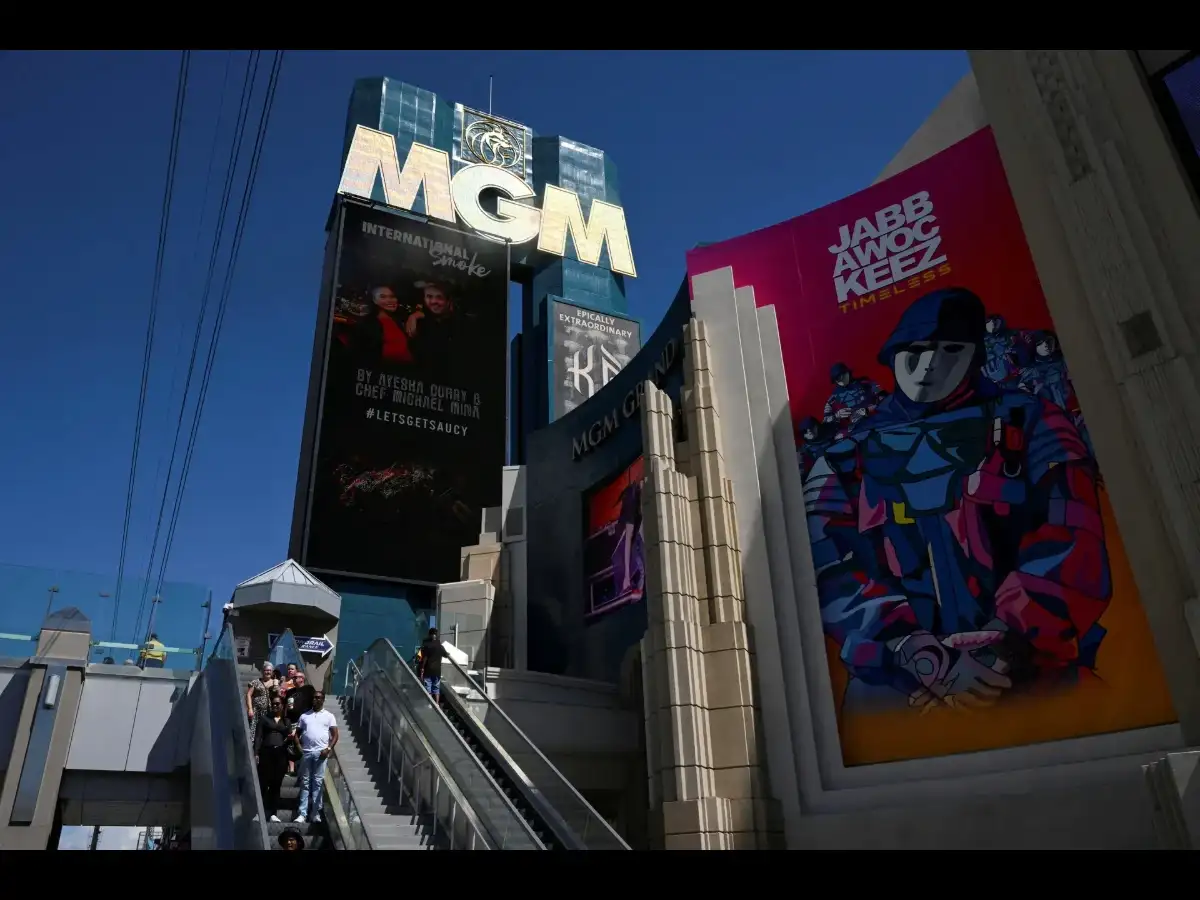
MGM controls marquee properties that account for roughly 40% of the Las Vegas Strip, but its growth has been patchy. Footfall in its core US market has been sluggish, even as its digital business and Chinese assets, including Macau, have held up well.
Analysts rate MGM "hold" on average, the same as peer Caesars, while smaller rivals Las Vegas Sands and Wynn Resorts carry "buy" ratings, according to LSEG data.
(Disclaimer: This article is based on inputs from agencies. These do not represent the views of The Economic Times)