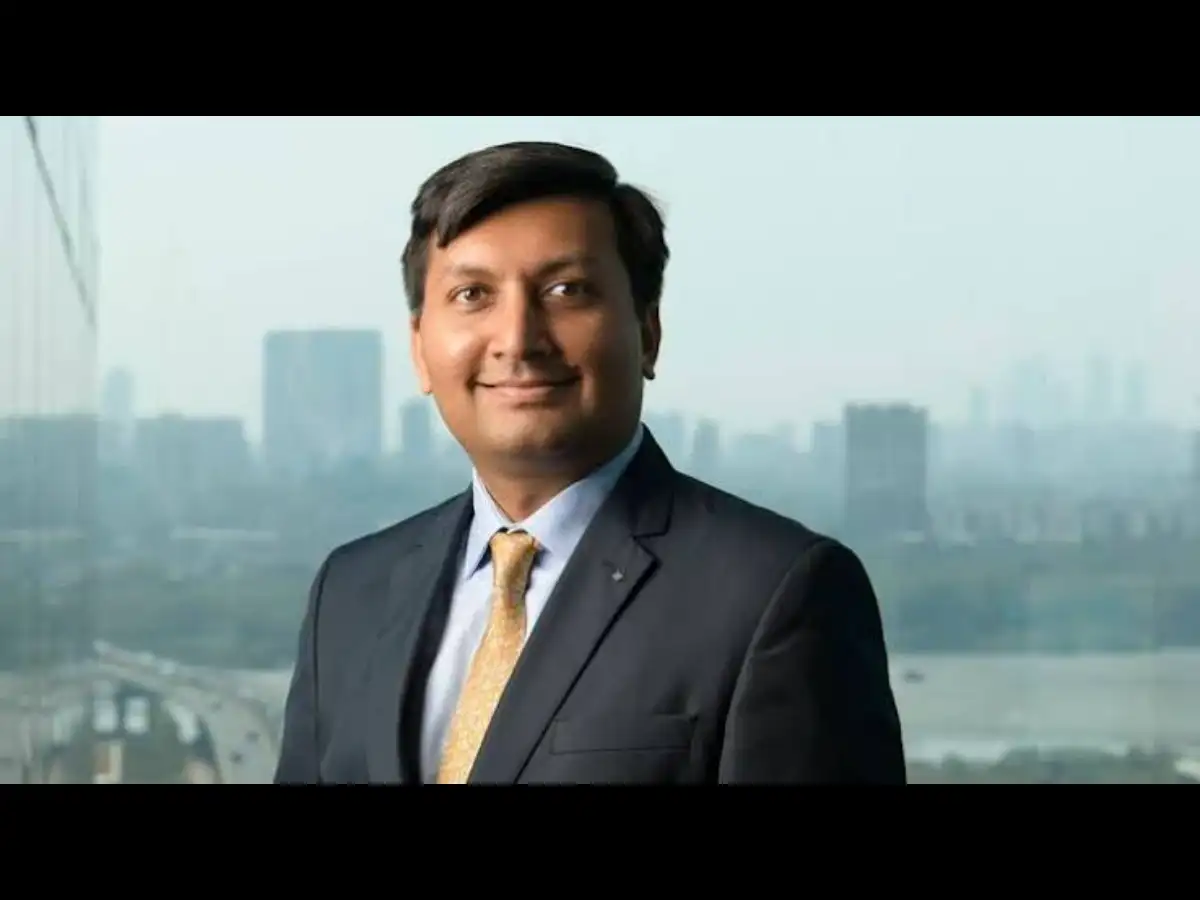
The threat artificial intelligence poses to traditional IT services appears to be largely reflected in Indian technology stocks, according to Chintan Haria, principal for investment strategy at ICICI Prudential AMC.
The Nifty IT index has fallen about 25% in 2026, bringing its valuation below that of the Nifty 50. Haria says the focus should now shift to companies that can adapt to AI and capture new demand in data engineering, cloud migration, legacy modernisation and AI integration. Edited excerpts from a chat:
The Nifty IT index has corrected about 25% in 2026, and its P/E has converged with the Nifty 50. Is this a genuine valuation reset, or does it reflect a structural downgrade in the sector’s earnings potential?
AI does challenge parts of the traditional IT services model, particularly work linked to manpower and routine application maintenance. However, valuations have already corrected sharply. So, much of the disruption risk appears to be captured in the current valuations with Nifty IT at around 17.6x P/E versus 19.2x for the Nifty 50. Now, the focus should be on companies that can adapt and participate meaningfully in new technology spending.
Investors initially feared that AI would displace Indian IT services. What has changed in the thesis, and how can AI instead create a fresh multi-year technology-spending cycle?
While AI can address some parts of the existing services, what tends to be overlooked is that AI adoption also creates newer requirements. Enterprises need to organise data, modernise legacy systems, migrate to the cloud etc. while integrating AI into their workflows. Indian IT companies have scale, delivery capabilities and established client relationships, which can aid them to participate in this next phase of technology spending.
Could AI-led spending become incremental to traditional IT budgets, or will enterprises largely fund it by reallocating spending from existing outsourcing and maintenance contracts?
Some portion of the AI spending will replace or make existing services more efficient, creating pressure on traditional revenue pools. But AI adoption also requires new investments. The key question is whether the new opportunities ultimately grow faster than the traditional areas that face disruption.
Which parts of the AI value chain offer the largest opportunity for Indian IT companies—AI integration, data engineering, cloud migration, cybersecurity, consulting or legacy modernisation?
The opportunity set is broad. Areas such as data engineering, legacy modernisation, cloud migration and AI integration are important because enterprises cannot effectively deploy AI without these underlying technology architectures in place.
How should investors distinguish between IT companies that are genuinely building AI-led capabilities and those merely using AI as a narrative to defend valuations?
Investors should look for indicators such as actual client adoption, revenue from AI-related services, productivity improvements, investments in capabilities and the ability to translate these investments into sustainable earnings. Eventually, AI should show up in business performance.
At current valuations, is the sector pricing in a normal recovery in discretionary spending, or does it already reflect a meaningful AI growth premium? Which segment of the IT universe appears most attractively valued?
Large-cap IT companies look compelling given their cash-rich balance sheet. At the current valuation, low growth is factored in. Any shift in the global AI narrative could lead to a significant rerating of the IT sector.
The Nifty IT ETF provides diversified exposure to the sector. Does its current composition adequately capture the emerging AI opportunity, or could its concentration in large legacy IT companies limit participation in newer technology themes?
We believe, over time, the IT sector will be able to capture emerging opportunities given the scale of operations and its ability to adapt to an ever-changing world. The IT Index is a reasonable way to participate in a sector which is currently out of favor, but has stood the test of time for over four decades.
For a five-year investor, should the current correction be viewed as an entry point into Indian IT, and what are the key risks that could invalidate the bullish AI-led thesis?
The recent correction has improved the valuation of the sector, but the space should be approached selectively. The key risks are faster-than-expected displacement of traditional services, pricing pressure, slower technology spending, and weaker-than-expected monetisation of AI investments. The companies that adapt successfully hold the potential to participate in the next technology-spending cycle.
Disclaimer: This article has been written by Nikhil Agarwal, who is not a SEBI-registered Research Analyst or an Investment Adviser. Nikhil Agarwal and his ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.