Shares of Jio Platforms, the country’s largest public offer to date, listed at Rs 1,358 on the BSE on Wednesday, an impressive 21.36% premium over the IPO price of Rs 1,119 per share. Jio Platforms’ IPO, with an issue size around Rs 30,200 crore, generated cumulative demand of more than Rs 7 lakh crore across the anchor and public book-building process.
The IPO was fully subscribed within 100 minutes of opening. Its Rs 5,500 crore qualified institutional buyer portion was subscribed within the first 10 minutes. At the close of the third day, the IPO had been subscribed 22.2 times, while the QIB portion was subscribed 70.55 times.
Why are brokerages bullish on the stock?
Nomura says disruptor is now the leader: International brokerage Nomura initiated coverage with a Buy rating and a target price of Rs 1,340, implying an upside of 20% from the issue price of Rs 1,119.
Also read: Jio Platforms shares list at 21% premium over IPO price. Should investors buy, sell or hold the stock?
Jio Platforms, India's largest telecom operator, held a 41.7% share of wireless subscribers, excluding M2M, in August 2026, according to TRAI. With the widest 5G coverage, data usage per subscriber 27% higher than Airtel and the lowest monthly churn rate among peers at 1.6%, Jio is well positioned to narrow its ARPU gap with Airtel, analysts say. A 15% industry-wide tariff hike in November-December 2026 could provide an immediate boost to ARPU.
With most of its 5G investment cycle behind it, Jio's capital expenditure (capex) is expected to decline, falling to around 23% of revenue in FY26 from 35% in FY25, freeing up significant cash flow and driving a sharp improvement in free cash flow (FCF). Nomura says Jio Platforms’ balance sheet is also strengthening, with net debt-to-equity, including deferred payment obligations, declining from 0.56 times in FY24 to 0.37 times in FY26. Nomura expects Jio to become debt-free on a net basis by FY29.
“Reliance Jio’s entry into the Indian telecom industry was a seminal event, which changed the rules of the game from minutes to megabytes, forcing the sector to consolidate from 12+ telcos before RJio’s launch to a 3+1 market structure,” the brokerage said.
Read more: Jio Platforms shares to be available under MTF from Day 1. What should investors know?
The brokerage believes Jio could command a premium to Bharti Airtel's India business in the near term, supported by its market leadership, greater influence over industry tariffs and a free float of less than 3%. However, its earnings and valuation estimates remain highly sensitive to growth in wireless average revenue per user (ARPU).
Also read: Ambani pulls off a blockbuster: Jio IPO makes 13 records, rewrites Dalal Street history
Jio’s digital springboard is affordability: Elara Capital has initiated coverage of Jio Platforms with a Buy rating and a target price of Rs 1,367 per share. Mobility will remain the primary driver of revenue and profitability, with the brokerage expecting subscriber additions to grow at a compound annual growth rate (CAGR) of 3% during FY26-29E, supported by affordable plans, an extensive network and low churn.
It also expects a tariff hike of 12-15% from H2FY27E. Along with 2G-to-4G and 5G migration, prepaid-to-postpaid upgrades, premiumisation, higher data consumption and bundled digital services, this is expected to drive average revenue per user (ARPU) from Rs 214 in FY26 to Rs 257 in FY29E.
Affordable data remains the foundation of Jio Platforms' ecosystem for consumers and enterprises. The company leverages its customer base and distribution platforms to integrate third-party services, reduce customer acquisition costs and deepen engagement. India's underpenetrated digital services market presents a structural growth opportunity across enterprise cloud, communications and consumer productivity solutions.
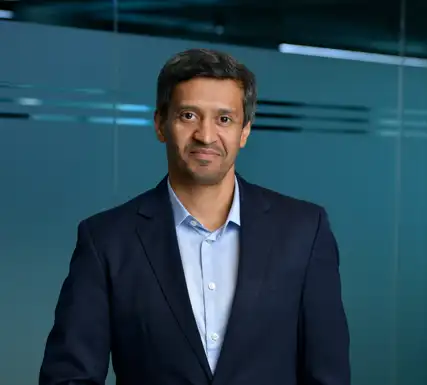
Speaking at Jio’s blockbuster listing on stock exchanges, Jio Platforms MD Akash Ambani said the company’s next phase would focus on “democratising every technology that can transform lives,” including AI, cloud, connected devices, connectivity from space and digital services yet to be imagined.
Disclaimer: This article has been written by Veer Sharma, who is not a SEBI-registered Research Analyst or an Investment Adviser. Veer Sharma and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.